Lucy Donovan
Head of Strategy & Communications
CCTA
The conference opened with a welcome from Mark Fiander, Chair of the CCTA, who greeted members, associates and industry colleagues and set the scene for a day of discussion on the issues shaping the sector. Jason Wassell, Chief Executive of the CCTA, followed with an introduction to the conference and its relevance to members, highlighting the importance of connecting regulatory developments with the day-to-day realities of smaller and specialist lenders. Responsible lending, proportionate regulation and the sustainability of access to credit provided a consistent thread throughout the day’s discussions.
Headline sponsor Walker Morris opened the substantive programme with Redress: friend or foe? Russell Kelsall and Paula Twist examined the evolving redress landscape and the implications of planned reforms for consumer credit firms. As the framework develops, understanding how changes may translate into operational and governance requirements will be increasingly important.
The discussion then turned to the wider challenges facing the sector in a fireside chat chaired by Mark Fiander. CEOs Mike Deans, Shiona Crichton and Chris Gillespie shared their perspectives on changing customer behaviour and the strategic decisions facing lenders as they seek to balance investment and growth with an evolving regulatory environment. The panel also considered reform of the Consumer Credit Act, and the changes they would like to see as the Financial Services Bill progresses through Parliament, highlighting the importance of a framework that remains fit for purpose as the market evolves.
Following the morning break, Alison Walters, Director of Consumer Finance at the Financial Conduct Authority (FCA), set out the regulator’s vision for a consumer credit market in which consumers can access suitable and affordable credit, responsible firms can innovate and grow, and emerging risks are identified before they lead to widespread harm. She emphasised the importance of evidence, proportionate regulation and collaboration in shaping the future of the market.
Alison explored the opportunities presented by digital customer journeys, data and AI, including the potential to improve access to credit and provide earlier support to consumers. She also highlighted the associated risks, including unaffordable borrowing and financial exclusion.
The FCA’s priorities include reducing unnecessary complexity, making more effective use of data to identify poor outcomes and enabling responsible innovation. She also confirmed that the FCA did not intend to undertake a second-stage review of the high-cost credit cap at this point, while retaining the option to reconsider its position if the evidence warranted it.
The subsequent regulatory panel with Alan Cathcart, Paul Godsmark, Lindsay Gustafsson and John Reynolds provided an opportunity to reflect on the FCA’s presentation and consider the practical implications of a changing regulatory environment for consumer credit firms. The discussion reinforced the value of constructive engagement between firms, regulators and industry representatives, particularly in ensuring that regulatory objectives translate into workable approaches that support good outcomes without overlooking the operational realities facing smaller lenders.
Before lunch, Andrea Cox of Equifax UK, the conference’s dinner sponsor, examined whether traditional approaches to affordability risk overlooking consumers whose circumstances do not fit established or “average” customer profiles.
Against a backdrop of economic uncertainty and changing patterns of income and expenditure, the session considered how richer, more timely data can help lenders develop a fuller understanding of individual circumstances, identify affordability risks and make better-informed lending decisions.
Jono Gillespie, CEO of Evlo, opened the afternoon programme with an overview of the organisation’s Financial freedom for everyone campaign. The campaign includes a call for rental payment data to be incorporated into credit files, with the aim of helping to improve financial inclusion. The session highlighted the potential for better recognition of consumers’ financial behaviour to support a more complete picture of creditworthiness.
The afternoon continued with a panel sponsored by Acquired, which explored how payments can contribute to better customer outcomes. Panellists considered how payments data can help firms recognise changing customer circumstances and respond appropriately, particularly where consumers may be vulnerable or experiencing financial difficulty. The discussion underlined the potential value of using data not simply to manage transactions, but to identify opportunities for timely and appropriate support.
Matthew Drage of Square 4 followed with an examination of outcomes testing under the Consumer Duty. Drawing on the FCA’s examples of good and poor practice, Matthew explored how firms can translate regulatory expectations into meaningful testing and practical action.
The final presentation before the closing keynote came from Cath Wohlers of the Illegal Money Lending Team (IMLT). Cath discussed the changing nature of illegal lending, including the extension of activity beyond traditional models into online and social media channels. The session also highlighted how regulated firms can work with the IMLT to help identify and support victims, reinforcing the importance of awareness, referrals and collaboration in tackling illegal lending and the harm it can cause
The final keynote was delivered by Kevin Wright, Ombudsman Leader at the FOS, who provided an update on complaint trends, developments in consumer credit and the modernisation of the redress system.
Kevin reported that complaint volumes had fallen by almost 30% in 2025/26, although early signs suggested that demand could be increasing again. Charging reforms had reduced complaints brought by professional representatives, while consumers continued to be able to access the service free of charge. Consumer credit remained a significant part of the FOS caseload, with issues including affordability, credit cards, loans and motor finance.
The session also considered preparations for potential motor finance redress referrals and the opportunities and challenges associated with AI in complaint handling. Kevin emphasised the importance of accuracy, fairness and human judgement as technology develops.
He outlined planned changes to the redress framework, including updated dismissal powers, a new registration stage and greater publication of complaint data and thematic insights. Effective collaboration between the FOS, regulators and industry will remain important in supporting a system that is faster, clearer and more consistent.
Jason Wassell brought the conference to a close by thanking the speakers, sponsors, delegates and everyone involved in organising the event. Across the day, a common theme emerged: the need to balance effective consumer protection and regulatory ambition with the practical realities of delivering credit in a changing market.
For over 130 years, we have championed responsible lending – supporting firms, engaging with policymakers, and shaping fair regulation. We provide insight, guidance, and a platform for businesses navigating a complex financial landscape.
Our work spans regulatory engagement, industry advocacy, and practical support, ensuring that consumer credit remains accessible, responsible, and sustainable. We provide the expertise and leadership that drive better outcomes for all.
Instalment Options on Request
sole traders & startups
From £80 per month
Paid annually at £950 +VAT
lenders & brokers
From £162 per month
Paid annually at £1,945 +VAT
associate firms
From £180 per month
Paid annually at £2,150 +VAT
Discounts Available

CCTA membership

CCTA academy

CCTA agreements
SUBMIT TO RECEIVE A QUOTE
 CCTA Membership
 CCTA Academy
 CCTA Conference
 CCTA Agreements
 CCTA Marketing
 CCTA Workshop - Outcomes Monitoring in SMEs
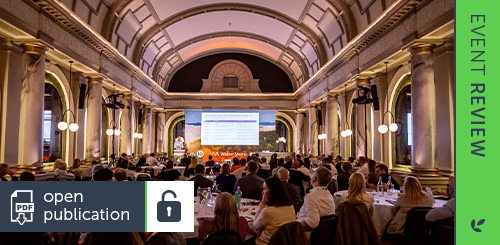 CCTA Conference - 2026 Event Review
 CCTA Conference - 2026 Event Brochure
 CCTA Inform - Summer 2026 Issue
 CCTA Magazine - 2026 Issue Two
 CCTA Guidance - New Complaints Reporting Process
 CCTA Guidance - NFM
 CCTA Guidance - SM&CR Reforms
CCTA Membership
CCTA Academy
CCTA Conference
CCTA Agreements
CCTA Marketing
CCTA Workshop - Outcomes Monitoring in SMEs
CCTA Conference - 2026 Event Review
CCTA Conference - 2026 Event Brochure
CCTA Inform - Summer 2026 Issue
CCTA Magazine - 2026 Issue Two
CCTA Guidance - New Complaints Reporting Process
CCTA Guidance - NFM
CCTA Guidance - SM&CR Reforms
